
Johnson Global partners with leadership of public accounting firms, driving change to achieve the highest level of audit quality. Led by former PCAOB staff, JGA professionals are passionate and practical in their support to firms in their audit quality journey. We accelerate the opportunities to improve quality through policies, practices, and controls throughout the firm. This innovative approach harnesses technology to transform audit quality. Our team is designed to maintain a close pulse on regulatory environments around the world and incorporates solutions which navigates those standards. JGA is committed to helping the profession in amplifying quality worldwide.

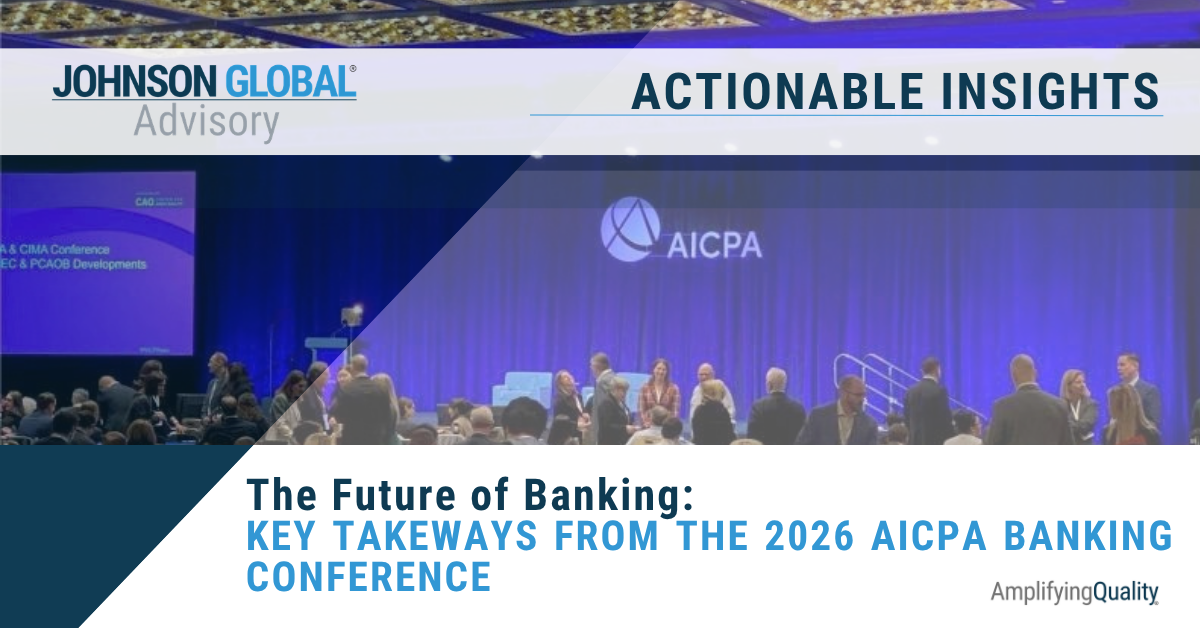
Overview The September 2026 AICPA Banking Conference highlighted three transformational developments affecting financial institutions: artificial intelligence (AI), digital assets, and regulatory modernization . Collectively, these trends signal a shift toward more technology-enabled banking, increased regulatory clarity around digital assets, and heightened expectations for governance, risk management, and controls. Artificial Intelligence: From Experimentation to Operational Deployment AI is rapidly becoming embedded across banking operations, including fraud detection, Anti-Money Laundering and Know Your Client (AML/KYC) monitoring, predictive analytics, risk management, and audit processes. Regulators and auditors increasingly expect institutions to establish formal governance over AI usage, including controls over data quality, model risk, cybersecurity, explainability, and human oversight. Audit methodologies are also evolving, with greater use of data analytics, continuous monitoring, and full-population testing. Banks that successfully implement AI governance frameworks may achieve operational efficiencies while reducing regulatory and audit risk. Digital Assets: Moving into Mainstream Banking The conference's strongest strategic message was that digital assets should now be viewed as financial infrastructure rather than speculative investments . Stablecoins, tokenized deposits, tokenized securities, and blockchain-based payment rails are increasingly being evaluated by banks as potential sources of growth and competitive advantage. At the same time, these developments create risks related to deposit migration, payment revenue disruption, liquidity management, and regulatory compliance. Regulatory initiatives, including implementation of the GENIUS Act framework and proposed SEC crypto rules, are accelerating institutional adoption and providing greater clarity around permissible activities. Management teams and boards should evaluate how digital assets may impact their business models over the next several years. PCAOB Developments: Greater Focus on Quality Control and Technology The PCAOB continues to make quality control systems a central inspection priority. The amendments to QC 1000 would reduce implementation burdens by eliminating certain requirements, including the External Quality Control Function and fixed September 30 evaluation date, while providing firms more flexibility in assigning responsibilities. Inspection findings remain concentrated in allowance for credit losses (ACL), fair value measurements, investment securities, internal controls, and accounting estimates. Technology, cybersecurity, fraud risk, and AI are becoming increasingly important inspection areas. Public-company banks should expect auditors to devote significant attention to data reliability, management-review controls, and documentation supporting key estimates. SEC Developments: Reduced Compliance Burden and Reporting Reform The SEC's regulatory agenda reflects a broad effort to modernize reporting requirements and facilitate capital formation. Key proposals include optional semiannual reporting, expanded Emerging Growth Company accommodations, filer-status simplification, registered-offering reform, and a proposed framework for crypto-asset offerings. If adopted, these initiatives could significantly reduce reporting and compliance costs for many public banking organizations while expanding access to scaled disclosure accommodations. Banks should continue monitoring these proposals, as they could materially affect reporting obligations, internal controls, and capital markets activities. Boards and management should prioritize: Establishing formal AI governance and risk-management frameworks. Evaluating strategic opportunities and risks associated with stablecoins and tokenized financial assets. Preparing for increased auditor and regulator focus on ACL, estimates, data quality, and internal controls. Monitoring SEC reporting reforms and potential compliance-relief opportunities. Assessing how technology investments can improve efficiency while strengthening governance and risk management. Conclusion The conference signaled that the banking industry is entering a new phase in which AI adoption, digital asset integration, and regulatory modernization are becoming mainstream strategic priorities. Audit firms will need to adapt their methodologies, quality control systems, technology governance, and staff capabilities to address these developments effectively. Our JGA experts can help assess emerging risks, strengthen quality-control and audit methodologies, enhance documentation and inspection readiness, and implement practical approaches for auditing AI-enabled processes, digital assets, complex estimates, and internal controls.
At Johnson Global Advisory, we believe in making a meaningful difference beyond our profession. We are proud to support Compassion International and its mission to help children overcome poverty through education, healthcare, life-changing resources, and hope. Through this contribution, we are investing in brighter futures for children, families, and communities around the world. We invite others to join us in supporting organizations like Compassion that are creating lasting change and transforming lives one child at a time.
In our previous alert, Open Board Meeting: PCAOB to Consider Adopting New Standards on General Responsibilities of the Auditor in Conducting an Audit, Quality Contro l, we discussed the PCAOB's plans to consider amendments to QC 1000 and related quality control reporting requirements. At its September 9, 2026 Open Meeting , the PCAOB adopted a series of amendments to QC 1000 and related reporting requirements designed to improve scalability, reduce implementation burden, and further align certain aspects of the standard with other quality management frameworks. While the amendments provide meaningful changes in several areas, firms remain responsible for establishing and maintaining an effective system of quality control starting December 15, 2026. The following table summarizes the key amendments adopted by the Board and JGA's insights regarding the implications for registered firms.